
Asia Petchem Chain Rattled by Hormuz Disruption as Plants Curb Output, Supply Fears Mount
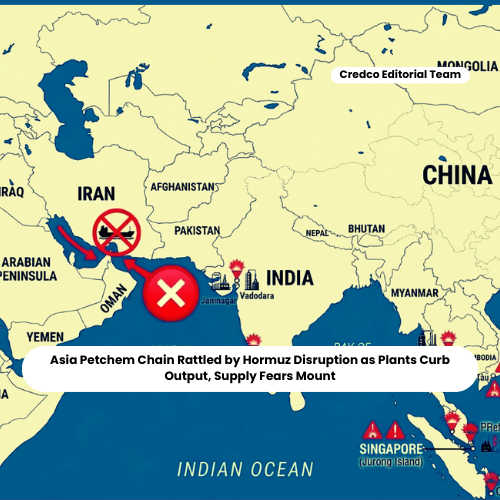
These disruptions have triggered force majeure declarations, plant shutdowns, and reduced operating rates at multiple facilities across Asia. As a result, the impact is now spreading through the region’s polymer and monomer markets, tightening supply and increasing price volatility.
Traders and converters are also facing rapidly rising offers and growing uncertainty regarding shipments and delivery timelines. Market participants warn that the supply chain could tighten further if the conflict continues to affect energy flows and shipping routes.
Feedstock Crunch Forces Producers to Curb or Halt Operations
Production disruptions have been reported across several countries in Asia as producers respond to feedstock shortages and logistical challenges.
Taiwan
Formosa Petrochemical Corp (FPCC): Declared force majeure and lowered operating rates. The No.1 cracker is offline, while PP, PE, and PVC supplies face disruptions, delays, and allocation measures.
China
LG Bohai Chemical: Declared force majeure affecting PVC and VCM operations at its Tianjin complex due to ethylene allocation issues.
CNOOC & Shell Petrochemicals Company (CSPC): One of two steam crackers at the Huizhou complex in Guangdong has been shut in a planned turnaround.
Wanhua Chemical: Declared force majeure on exports of PP, PE, and PVC to the Middle East.
PetroChina Guangxi Petrochemical: Lower operating rates at ethylene and propylene crackers.
Tianjin Bohua / Sinopec Shijiazhuang / PetroChina Dagang: Shutdowns reported at PP units.
Zhong An United Coal: Planned shutdown of PP and PE units.
Fujian Refining & Petrochemical: PP and PE units shut while the rest of the complex is running at about 30% lower rates.
Sinopec Zhongke: Run rates reduced by about 10% at cracker, PP, and PE units.
Zhejiang PC: Run rates cut by about 20% at cracker, styrene, PP, and PE units.
South Korea
YeoChun NCC: Declared force majeure, with naphtha crackers operating at minimum capacity.
Hanwha Total Petrochemical: Lower operating rates at two ethylene crackers.
Hanwha Solutions: Declared force majeure on EDC supply and temporarily shut one chlor-alkali production line.
Lotte Chemical: Warned of potential operational disruptions and possible force majeure at olefins, PP, and PE plants in Yeosu and Daesan.
Japan
ENEOS Corp: Declared force majeure on paraxylene (PX) supply.
Malaysia
PRefChem: Shutdown of its 1.2 million tons/year cracker and two RFCC units.
Singapore
The Polyolefins Company (TPC): Declared force majeure and halted several polyolefin production lines including LDPE, EVA, and PP.
PCS Pte Ltd: Declared force majeure due to olefins supply disruption.
Aster Chemicals and Energy: Declared force majeure affecting styrene units and one ethylene/propylene cracker.
Vietnam
Hyosung Vina Chemicals: Reduced operating rates at its propane dehydrogenation (PDH) unit.
Long Son Petrochemicals: Warned of operational disruptions, with cracker, PP, and PE units running at lower rates due to feedstock supply risks.
Thailand
Siam Cement Group (SCG): Declared force majeure at the Rayong Olefins complex.
AGC Vinythai: Warned of possible shipment delays for PVC due to maritime disruptions.
Indonesia
Chandra Asri: Declared force majeure and lowered operating rates at cracker, PP, and PE units.
Lotte Chemical Titan: Lower rates at crackers producing 1 million tons/year of ethylene and 520,000 tons/year of propylene.
India
ONGC Petro additions Ltd (OPAL): Lower operating rates at its ethylene (1.1 million tons/year) and propylene (400,000 tons/year) crackers.
Mangalore Refinery and Petrochemicals Ltd: Shutdown reported in part of its refining operations including PP and propylene units, with force majeure status not confirmed.
Regional Polymer Markets See Extreme Volatility
Market participants across Asia say the war has created an unprecedented level of volatility in polymer and monomer markets, with prices rising sharply while trading activity remains limited.
PP and PE markets:
China’s domestic markets, along with Vietnam and India, have seen major price spikes this week, with prices changing almost daily.
PVC markets:
China’s export prices have reached a three-year high, while India’s import prices have climbed to their highest levels in three and a half years. Meanwhile, PVC markets in Southeast Asia have surged to their highest point since July 2022.
As feedstock disruptions continue and multiple plants operate at reduced rates or remain shut, market participants expect tight supply conditions and continued volatility across Asia’s petrochemical markets in the coming weeks.
Stay ahead of market trends with the Credco app. For any queries, please reach out to us via WhatsApp at +918448083211
Related on the Wire
- Supply·Monday, 2 November 2026
Indian Polymer Markets Begin November with Broad Price Increases, PVC Leads
India’s domestic PP, PE and PVC markets started November with notable price hikes, as major producers issued upward revisions effective November 1. Suspension PVC (S-PVC) recorded the most substantial increase, while polypropylene (PP) and several polyethylene (PE) grades also…
Read story - Polymer·Wednesday, 16 September 2026
India’s Domestic Polymer Prices Gain Further Support as Import Costs Rise
India’s domestic polymer market has entered another phase of price increases, with major producers raising prices across PP, PE and PVC as higher international resin values, energy costs and freight rates lift import replacement costs. The recent revisions are giving domestic …
Read story - Supply·Friday, 25 September 2026
Tight Supply Supports October PP and PE Outlook in Turkey
Polyolefin markets in Turkey are expected to end September with supply availability playing a larger role than production costs. PP and PE prices continued to rise during the month, with limited availability becoming the key factor behind the latest increases. Crude oil prices…
Read story - Supply·Thursday, 24 September 2026
Tight Supply Keeps Turkey Polyolefins Firm Ahead of October
Polyolefin markets in Turkey are heading toward the end of September with supply availability playing a bigger role than production costs. PP and PE prices continued to rise during the month as limited availability became the key factor supporting the market. Despite sharp flu…
Read story